Signing a Medical Authorization Form for an Insurance Claim
By Mason ArnaoPublished
By Mason ArnaoReviewed by Mason Arnao
You often have more say than the form suggests. With a medical authorization form insurance claim adjusters send after a car accident, you can usually narrow what it covers or send the relevant records yourself, and what it lets the insurer see depends on its wording: a valid HIPAA authorization must describe the information to be disclosed, who may release it, who receives it, the purpose, and an expiration date, so a broadly worded form can reach far more of your health history than the injuries from this crash.
Signing that form is not the only way your records can reach an adjuster. Federal law gives you a legal, enforceable right to see and get copies of your own records from your doctors and health plans. That means you can review your records first and then decide what to share.
This guide explains what a blanket authorization can open up and why a request from your own insurer differs from one sent by the other driver’s company. It also covers how to limit a release by dates, providers, and purpose, how to request your records directly, and what you can do if the adjuster insists on a broad release or your claim stops moving.
The short answer: you can usually choose how your medical records reach the insurer
A medical authorization form is your written permission for doctors, hospitals and other providers to send your health records to the insurance company. Under the HIPAA Privacy Rule, a provider generally may not use or disclose your protected health information without a valid authorization unless the rule otherwise permits or requires it. That is why the adjuster is asking for your signature. Without it, your providers generally cannot send your records straight to the insurer.
The adjuster’s underlying request is reasonable. They need medical proof to evaluate an injury claim. What matters is how much of your medical history they get and by what route. A form that covers every provider and every year of your life reaches much further than one limited to the treatment you received after the accident.
In most cases you have three practical options:
- Sign the form as written. This is the fastest option, but it may allow the insurer to collect records unrelated to your injury.
- Sign a narrowed version. You can limit the release to specific providers, dates and a stated purpose.
- Get the records yourself. You can request your accident-related records from your providers and send the insurer only the relevant ones.
The sections below explain each option, the difference between dealing with your own insurer and the other driver’s insurer, and what to do if an adjuster pushes back. This guide explains the process and is not legal advice. Legal Lawsuit is not a law firm. To see where the medical records step fits in the overall process, read our guide on how a car accident claim works from start to finish.
What a blanket medical authorization lets an adjuster obtain
A medical authorization is your written permission for doctors, hospitals and other providers to send your health information to someone else. Federal rules in 45 CFR 164.508, which sets out what a valid HIPAA authorization must contain, require the form to include:
- A description of the information to be disclosed
- Who may disclose it, meaning the providers or types of providers releasing records
- Who may receive it
- The purpose of the disclosure
- An expiration date or event
- Your signature and the date
The description field matters most. If it reads like “any and all records” and the provider line says “any provider,” the form can reach records from years before the crash. Those can include prior treatment, prescriptions or counseling that have nothing to do with your injuries. Once an adjuster has that history, it can become part of the conversation about your claim. For more on that, see how adjusters handle statements, releases and early offers.
The same rule requires several statements that are easy to skim past:
- Redisclosure warning: Once information is disclosed under the authorization, the recipient may share it again, and it may no longer be protected by the federal Privacy Rule.
- Right to revoke: The form must tell you that you can revoke it in writing, and explain any exceptions.
- Plain language: The form must be written so you can understand it.
- Your copy: If a HIPAA-covered entity asks you to sign the authorization, it must give you a copy of the signed form.
Before you sign, read every field and check each of these points:
- Which provider names are listed
- What date range the form covers
- Who the recipient is
- What purpose the form states
- When it expires
A blank or open-ended field is worth questioning before your signature goes on the page.
Your own insurer vs. the other driver’s insurer: why the request is different
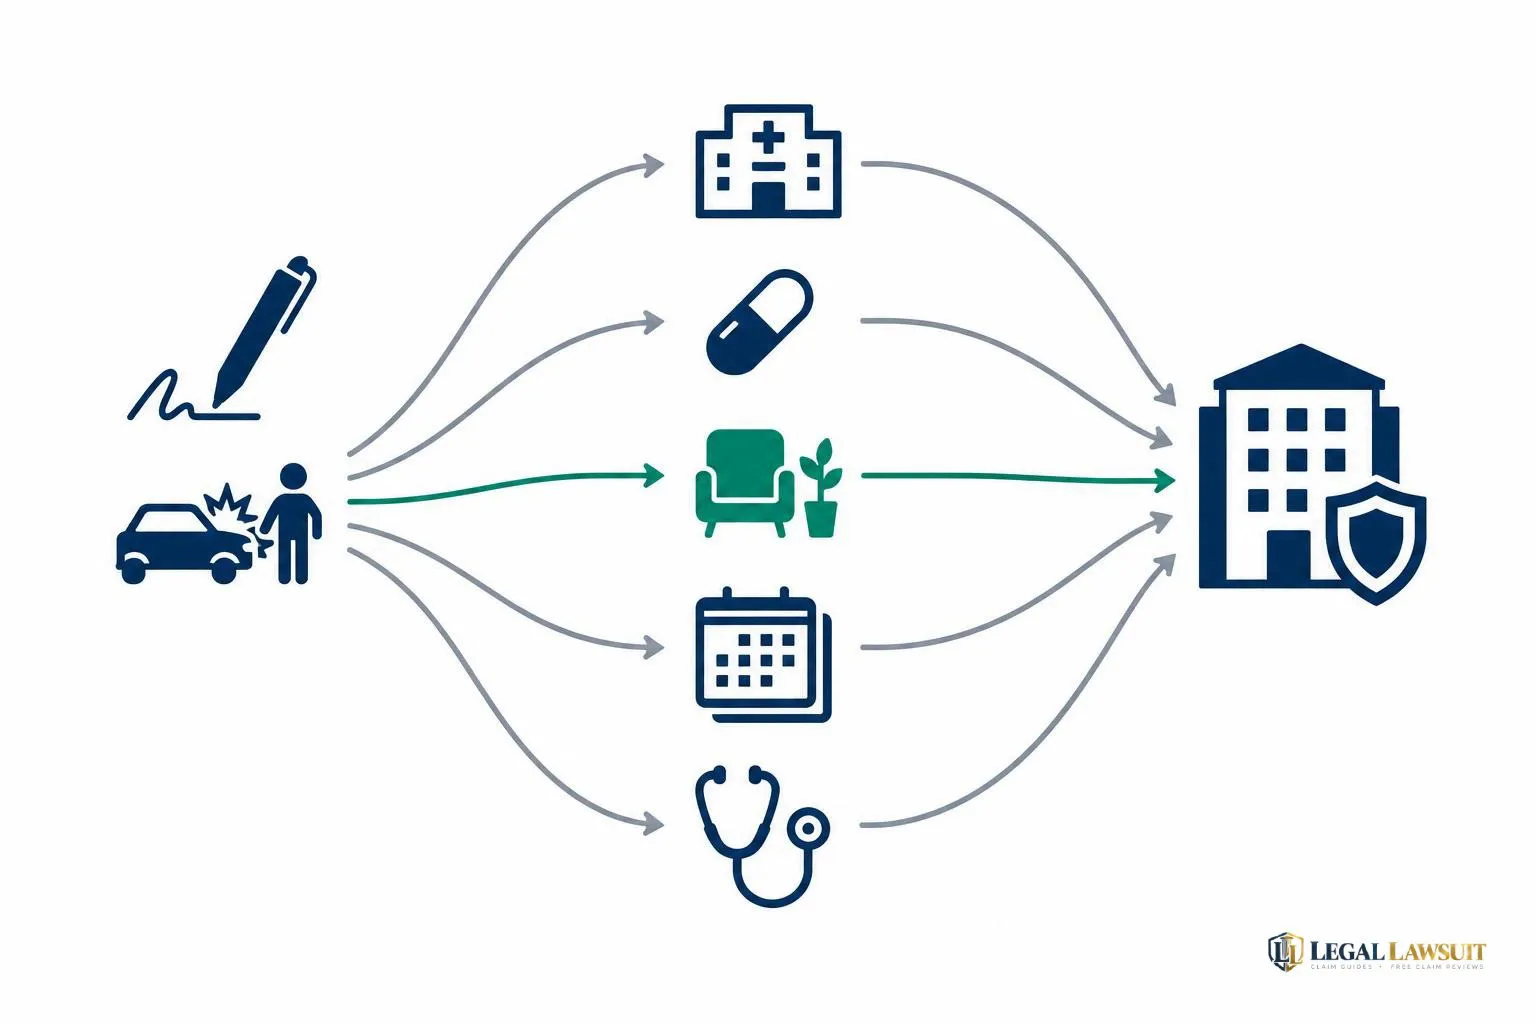
Who is asking for your records matters. The authorization request looks the same on paper, but your relationship with the company asking for it is not.
A first-party claim: your own policy
When you claim benefits under your own policy, you have a contract with that insurer. Many policies include a section on your duties after a loss or on cooperating with the company. Read that section before you respond, so you know what your policy actually asks of you and can decide how to provide the information.
Revoking a HIPAA authorization also has a limit tied to insurance. You can generally revoke in writing. But if you signed the authorization as a condition of getting insurance coverage, the federal HIPAA authorization rule says revocation does not take away an insurer’s right to contest a claim under the policy, or the policy itself, where other law gives it that right.
A third-party claim: the at-fault driver’s insurer
When you claim against the other driver’s insurer, you have no policy contract with that company. Its adjuster represents its own policyholder, not you. That makes it reasonable to think carefully about what you sign and how much you share.
State rules for insurers’ authorization forms
State insurance law can set rules for the forms insurers use. In California, Insurance Code section 791.06 requires an insurer’s disclosure authorization to:
- Be written in plain language
- Be dated
- Specify the nature of the information it covers and the purposes for collecting it
- State how long it remains valid
For a claim that is not for a health insurance benefit, the authorization can be valid no longer than the duration of the claim. You are also entitled to a copy of the form.
These choices often come up twice in the same accident. If you are filing a pedestrian accident insurance claim or filing a motorcycle accident insurance claim, you may be dealing with your own coverage and the other driver’s insurer at the same time. Each company may send its own medical authorization request.
How to limit a medical release by date range, provider and purpose
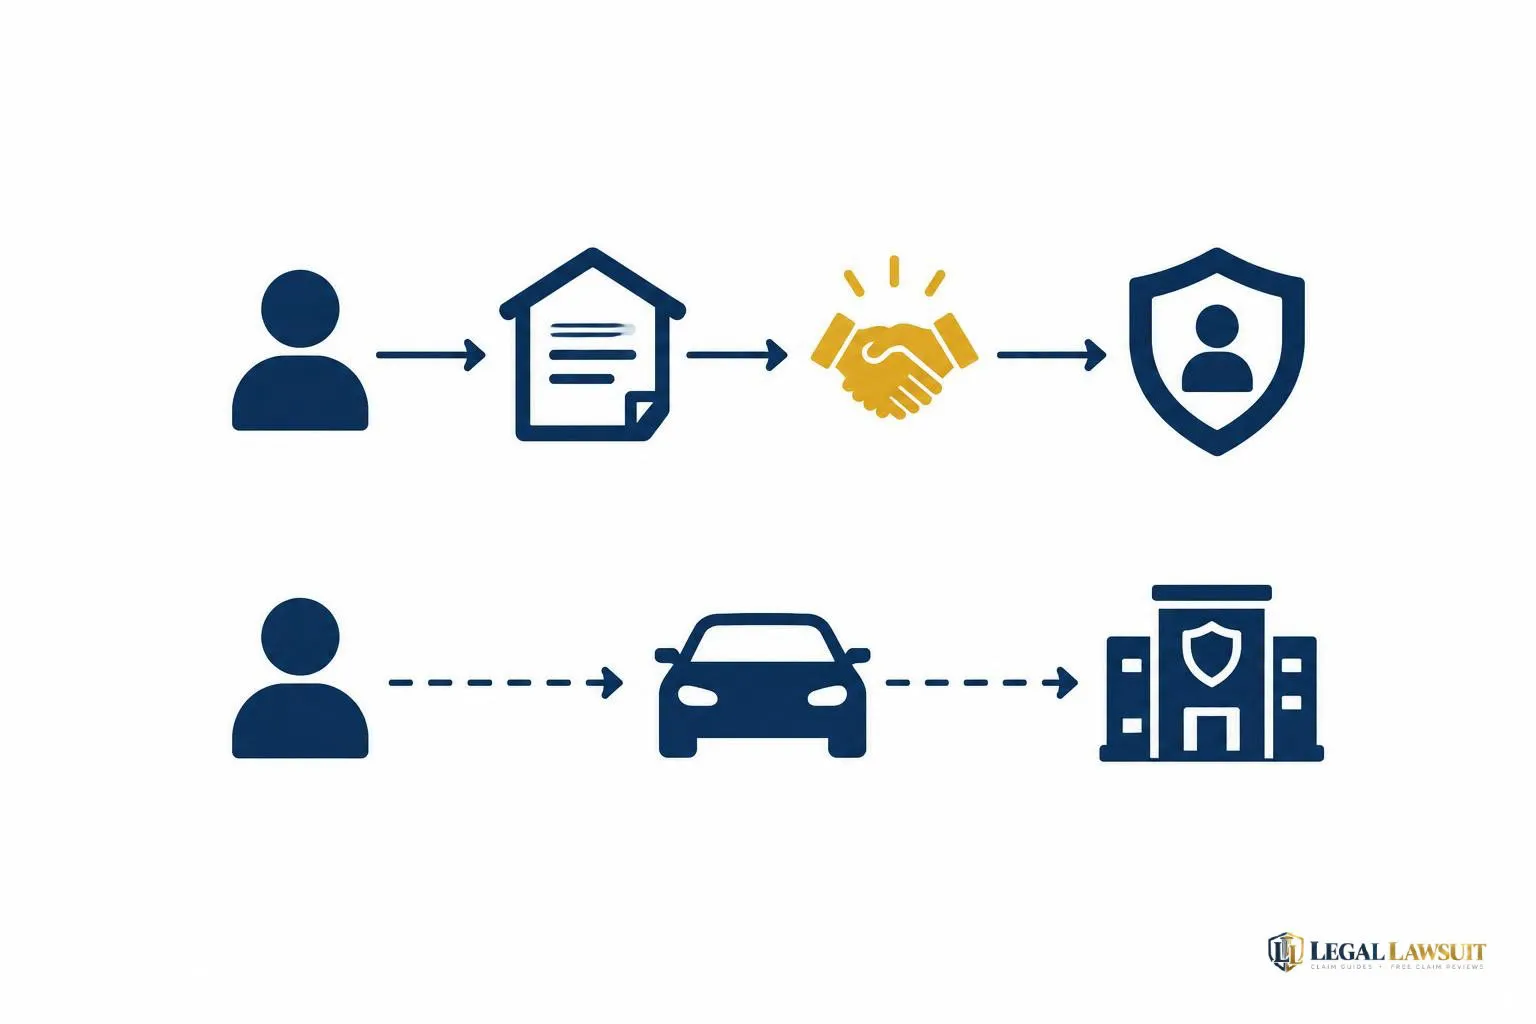
You don’t have to accept an open-ended form to cooperate with a claim. Under the federal HIPAA authorization rule (45 CFR 164.508), a valid authorization must describe the information to be disclosed, name who may disclose it and who may receive it, state the purpose, include an expiration date or event, and carry your signature and the date. Each of those required pieces is a place where you can set reasonable limits.
Ways to Narrow a Medical Release
Crash-related records only
Limit the description to treatment for injuries from the accident.
Start at the accident date
Set a date range that begins on the day of the crash.
Name specific providers
List the providers who treated you instead of 'all providers'.
One named recipient and purpose
Name the insurer and claim, and state the purpose as evaluating that claim.
Clear expiration
HIPAA requires an expiration date or event on every valid authorization.
Keep a copy
You can revoke a HIPAA authorization in writing, with limited exceptions.
- Description and date range: Instead of “any and all records,” write something like: “Records of treatment for injuries from the motor vehicle collision on [accident date], from [accident date] forward.”
- Providers: List by name each doctor, hospital, clinic or therapist who treated you for the crash. Avoid “all providers.”
- Recipient: Name one recipient, meaning the adjuster’s insurance company, and include the claim number.
- Purpose: State it plainly, for example: “Evaluation of claim number [number] only.”
- Expiration: Choose a specific date or a clear event, such as “upon final resolution of claim number [number].” The same federal rule requires an expiration date or event on every valid authorization.
Keep a copy and know how to revoke it
Keep a copy of every authorization you sign so you know exactly what you allowed. Under the same regulation, you can revoke a HIPAA authorization in writing at any time. The revocation does not undo anything a provider already did in reliance on the authorization before receiving your revocation.
Narrow, but don’t hold back what matters
The goal of these limits is relevance. You are not trying to hide anything. Records about the injuries you are claiming, including earlier treatment for the same body part, may be part of what the insurer reasonably needs. Never leave out or change records that relate to those injuries. A focused, accurate release protects your privacy and keeps your claim credible.
Supplying the records yourself using your HIPAA right of access
Instead of signing a release, you can request your medical records yourself, review them, and send the insurer only the records that relate to your claim. This keeps you in control of what the adjuster sees.
Getting Your Own Records Under HIPAA
Step 1: Ask each provider
Request copies of your accident-related records and bills from each provider's records office.
Step 2: Choose a format
Ask for paper or electronic copies. You can also have an electronic copy sent to a third party.
Step 3: Provider responds
The provider must act within 30 calendar days, or no more than 60 if it notifies you of an extension.
Step 4: Expect a limited fee
Any fee must be reasonable and cost-based, covering only certain labor, supplies and postage.
Step 5: Review, then send
Check the records for accuracy and send the relevant ones to the adjuster.
Your right to get copies
HHS explains that, with limited exceptions, the Privacy Rule gives you a legal, enforceable right to see and get copies of your records from your health care providers and health plans. A provider must act on your request no later than 30 calendar days after receiving it. If it notifies you of an extension, it has no more than 60 calendar days in total. You can also ask for copies in the form and format you prefer, including electronic copies, when the provider can readily produce them that way.
Providers may charge you a reasonable, cost-based fee. According to the HHS right of access FAQs, that fee can cover only certain labor, supply and postage costs.
A simple way to handle it
- Request records from each provider who treated you for your claim-related injuries. Include the dates of treatment you need.
- Ask for itemized bills along with the records, so you have both treatment and costs in one place.
- Check everything for accuracy. The HIPAA Privacy Rule gives you the right to request corrections to your records. It also lets you direct a provider to send an electronic copy to a third party.
- Send only the relevant pages to the adjuster. Keep a complete copy of everything you send.
Many claimants send their records and bills together with a demand letter. If you are at that stage, our guide to writing a demand letter that includes your medical records walks through how to organize them.
If the adjuster insists on a broad release or the claim stalls
If the adjuster won’t accept a limited release, you can keep the conversation going without signing something you’re uncomfortable with. Ask questions, offer what’s relevant, and keep a clear paper trail.
Ask why, in writing
Send a short letter or email asking why the adjuster needs records outside your crash-related treatment and the date range you offered. Ask which providers or time periods they think matter and why. Keep copies of every letter and email you send and receive, along with notes of phone calls (date, name, what was said). A written record makes it easier to show what you offered and when.
Offer what you have, and be truthful
Send the accident-related records you’ve already gathered so the adjuster has something concrete to review. If you’re asked about earlier injuries or treatment to the same body part, answer honestly. Limiting a release controls how much of your history leaves the provider’s office. It is not a way to hide relevant facts, and being caught in an inaccurate answer can hurt a claim far more than the history itself.
The release and a recorded statement are separate
Adjusters sometimes ask for both at once, but they are different requests. Agreeing to one does not commit you to the other. If that request is on the table too, it’s worth reading up on whether you have to give a recorded statement before you decide.
Revoking a broad form you already signed
Under federal privacy rules, you can revoke a HIPAA authorization in writing. Send a written revocation to each provider named on the form. Revoking stops future disclosures but does not undo anything a provider already did in reliance on the form. There are also exceptions, including some authorizations signed as a condition of getting insurance coverage.
If the claim stalls or is denied
If the insurer refuses to move forward or denies the claim, our guide on what to do if car insurance denies your claim walks through your options. Legal Lawsuit’s guides can help you work out where you stand. No outcome is guaranteed.
Frequently asked questions
Do I have to sign the other driver’s insurance company’s medical authorization?
Signing is your decision. Under HIPAA, your doctors and hospitals generally need your valid written authorization before disclosing your health information for a purpose like a third party’s claim review. An adjuster asking for your signature is making a request. Agreeing to a broad form is not the only way to show the insurer your injuries.
Another option is to keep control of the process. You have the right to get copies of your own health records and direct an electronic copy to a third party. That lets you send records about the accident injuries instead of your full medical history.
Can I take back a medical authorization I already signed?
Usually, yes. Federal rules let you revoke an authorization at any time, as long as you do it in writing. Send your written revocation to each provider named on the form, and keep a copy for your records.
A revocation has limits. It does not undo disclosures a provider already made while relying on your authorization. It also may not apply if you signed the form as a condition of getting insurance coverage and another law gives the insurer the right to contest a claim under that policy.
How long does my doctor or hospital have to give me copies of my records?
Under HIPAA, providers and health plans must act on your request within 30 calendar days. If they need more time, they can take one extension of up to 30 more days. They must notify you of the extension, so the total time is no more than 60 days. Ask early if you have a claim deadline, and write down the date you made your request.
Can a provider charge me for copies of my own medical records?
A provider can charge a fee, but HIPAA limits what that fee can include. According to HHS, the charge is limited to certain labor, supply and postage costs tied to making and sending your copies. If a bill seems high, you can ask the provider’s records office to explain how they calculated it.
Does a signed medical release ever expire?
Yes. A valid HIPAA authorization must include an expiration date or an expiration event, such as the end of a claim. Read that line before you sign. If it is blank or vague, you can ask for a specific end date that matches your claim.
Some states add their own rules. In California, insurer disclosure authorizations for claims other than health claims stay valid only for the duration of the claim, and you have the right to a copy of the form.
Sources
- Individuals' Right under HIPAA to Access their Health Information 45 CFR § 164.524 · U.S. Department of Health and Human Services
- 45 CFR 164.508 — Uses and disclosures for which an authorization is required · Electronic Code of Federal Regulations (eCFR)
- The HIPAA Privacy Rule · U.S. Department of Health and Human Services
- Right to Access and Research (HIPAA FAQs) · U.S. Department of Health and Human Services
This article is general information, not legal advice. Laws and deadlines vary by state and change over time; check the linked sources or speak with a licensed attorney about your situation.
Related Posts

Who covers your rental after a crash depends on fault, the coverage you bought, and whether your car is repaired or totaled. This guide covers the three ways a rental gets paid for, what limits the rental, and what to do while the other insurer is still deciding fault.
Build a practical family plan for phone use, passengers and distractions before your teen drives. Find a separate path to claim guidance if a crash has already happened.
La ley de moverse al lado de Florida ya no protege solo a policías y ambulancias. Aquí verás qué vehículos y situaciones cubre según el estatuto 316.126, qué debe hacer cada conductor y qué conviene saber si te chocaron mientras estabas detenido en el arcén.